Newsletter | Your Monthly Finance Tips
Monthly Finance tips - October 26
- Details
 Another RBA decision is looming, and borrowers could face yet another rate rise. But there are also opportunities emerging in the property and lending markets – here's what you need to know:
- Five mortgage checks to make before the next RBA decision
- Rental growth stalls despite Australia's housing shortage
- More lenders join the government's Help to Buy scheme
- The lending loophole some borrowers may not know about
Call me now on: 0402 408944
Five checks before the next rate decision
Another interest rate rise is possible in November – but there are steps you can take now to protect your household budget.
The Reserve Bank of Australia (RBA) raised the cash rate again in late September, prompting lenders across the market to increase their variable mortgage rates.
That was the fourth increase of 2026, and persistent inflation means another rise at the RBA's 3 November meeting remains possible.
Five things worth checking now
1. Your interest rate. Is it still competitive, or could another lender offer a better deal?
2. Your repayments. Calculate what another 0.25-percentage-point increase would mean for your budget.
3. Your cash buffer. Could you cover unexpected expenses alongside higher repayments?
4. Your offset account. Are you making full use of any interest-saving features?
5. Your loan structure. Would refinancing or changing your repayment arrangements make sense?
Another rate rise isn't guaranteed, but there's no harm in being prepared.
Get in touch and I'll help you assess whether your current mortgage is still competitive and how you could manage higher repayments.
Rental growth stalls despite housing shortage
Rents have stopped rising in some markets despite a shortage of available homes – a surprising shift that could affect investors and first home buyers.
Domain's latest rental figures suggest affordability pressures may finally be putting the brakes on rent increases.
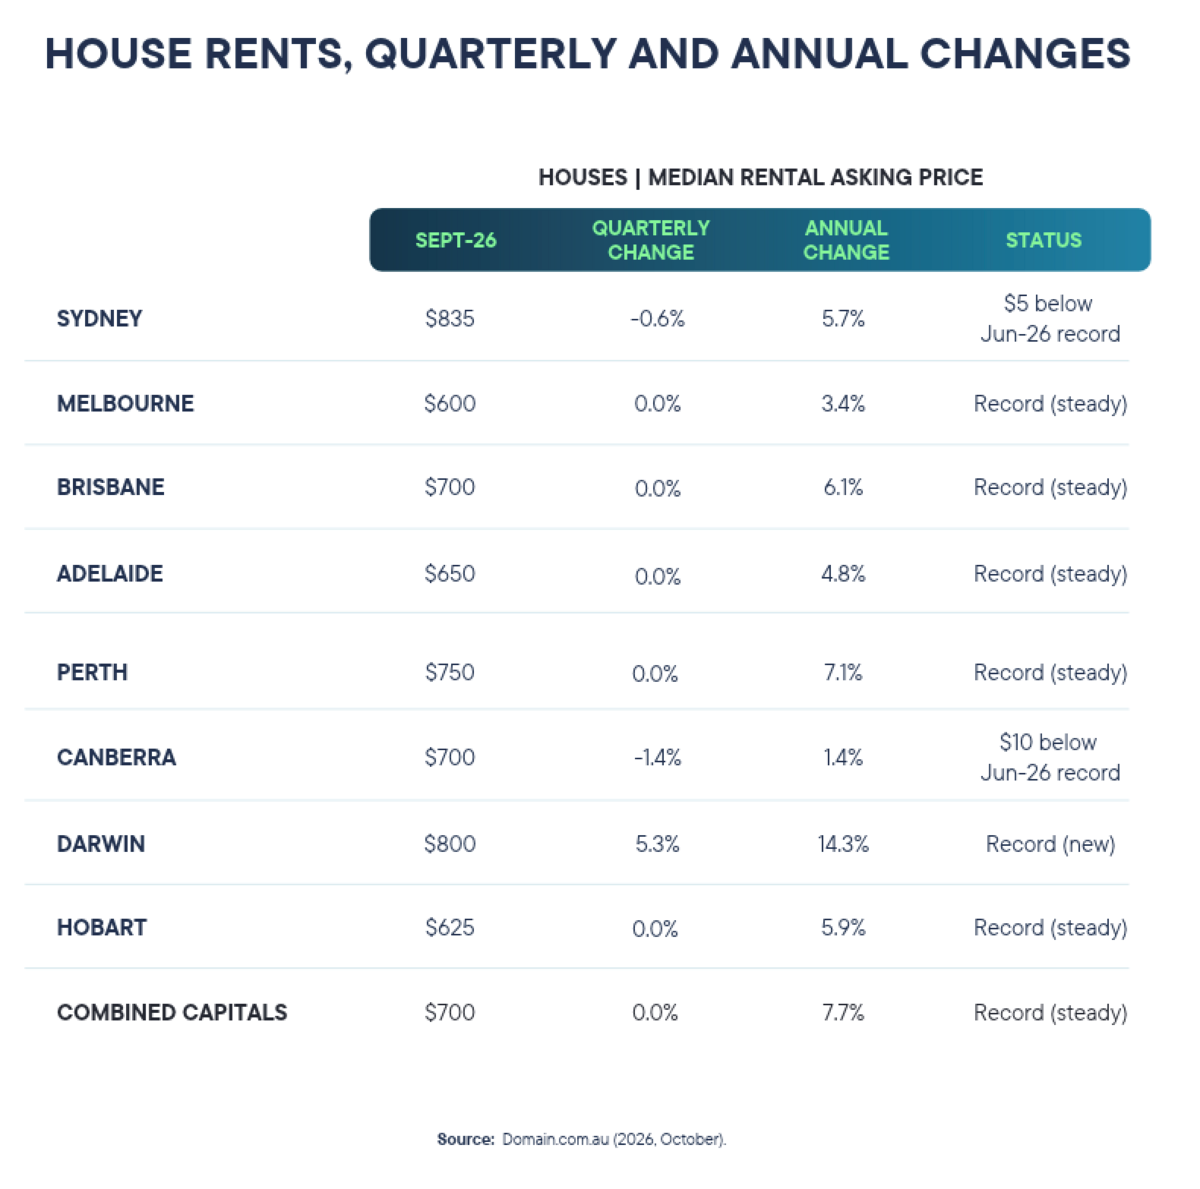
Across the combined capital cities, the latest figures show:
- House rents rose 7.7% over the year to September but 0.0% over the quarter.
- Unit rents rose 6.2% in annual terms and 1.5% in quarterly terms.
 One possible explanation is that renters are reaching their affordability limits after years of sharp increases.
For investors, low vacancies remain encouraging, as they suggest continued demand for rental accommodation. However, conservative rental forecasts and careful cash-flow planning are becoming more important.
For first home buyers, slower rent growth could provide some breathing room to build a deposit, although rents remain high.
Thinking about buying your first home or an investment property? Let's work through the numbers to see what you could comfortably afford.
More lenders join Help to Buy
Buying your first home could be more achievable than you think – with the federal government's Help to Buy scheme allowing eligible buyers to enter the market with a deposit as small as 2%.
An additional lender has now joined the scheme, expanding the options available to eligible buyers.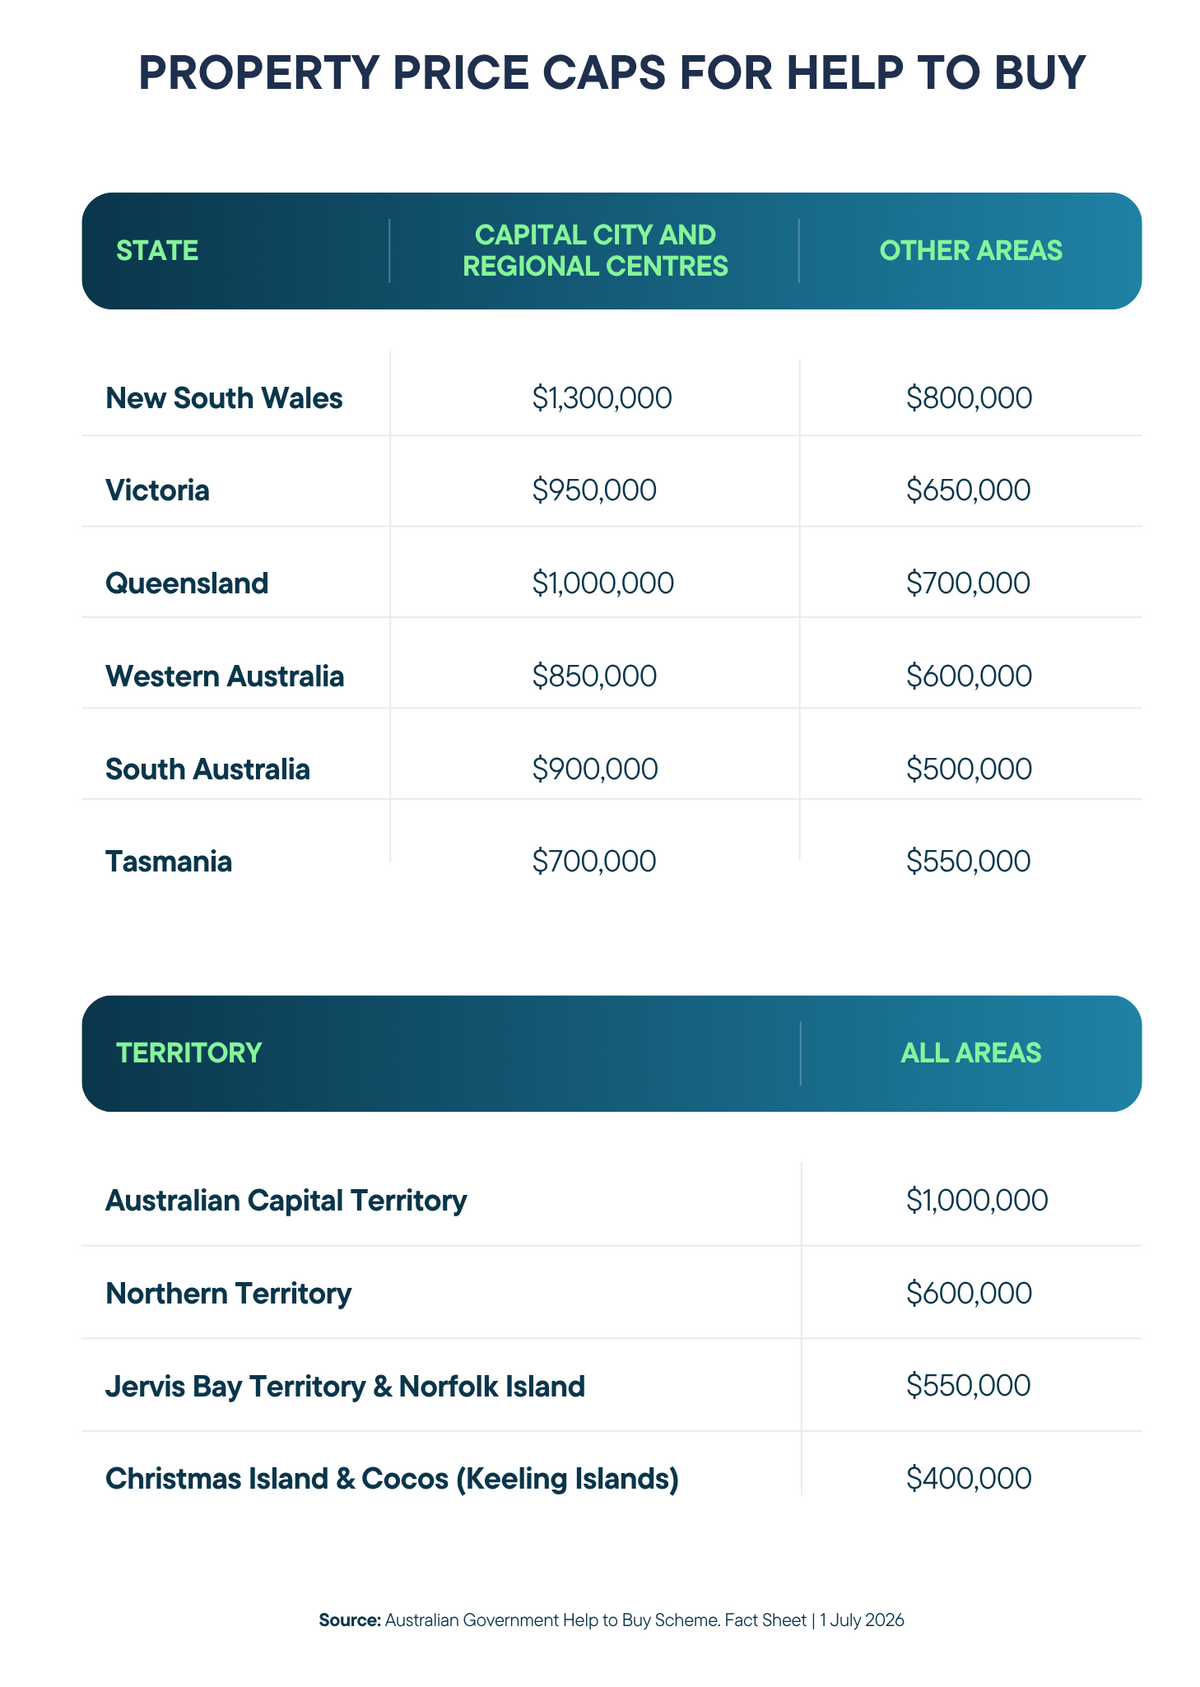 How Help to Buy works
- You need a deposit of at least 2%.
- The government contributes up to 30% of an existing home's purchase price or 40% of a new home's price.
- You borrow the remaining amount from a participating lender.
- The government retains an equity share, which generally changes in value as the property value changes.
The scheme has income limits, property price caps and other eligibility conditions.
For qualifying buyers, the smaller mortgage could mean lower repayments and an earlier entry into home ownership.
Help to Buy could make home ownership possible sooner than you expected. I can help you understand the eligibility requirements and how the scheme might work for you.
Lending exceptions become more common
Being outside a lender's standard borrowing criteria doesn't always mean your home loan application will be rejected.
New figures from APRA, the banking regulator, show that 5.8% of loans funded in the June quarter involved exceptions to lenders' standard serviceability policies, up from 5.1% in March and 4.8% a year earlier.
Serviceability is a lender's assessment of whether you can afford your mortgage repayments, including a buffer for possible rate increases.
In some cases, a lender may approve a loan that falls outside its usual serviceability rules, provided the borrower can still demonstrate an acceptable ability to repay.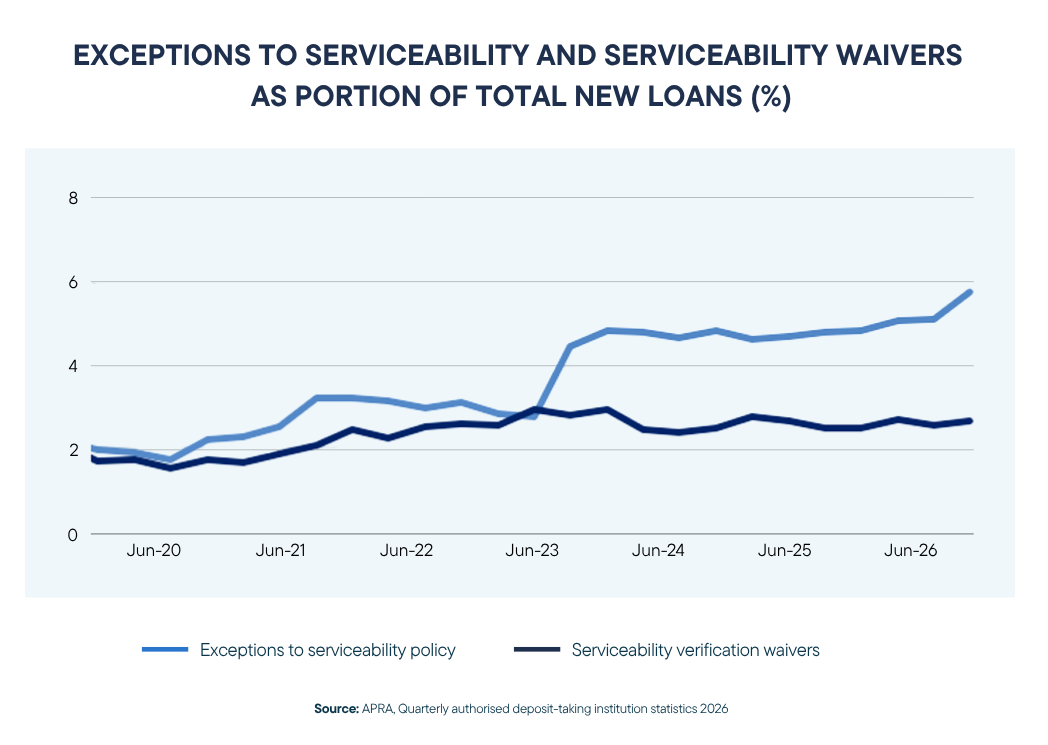 Why this could be encouraging
A borrower with a strong repayment history might be able to refinance even if they don't satisfy the usual assessment requirements.
Similarly, someone experiencing a temporary income reduction might have other evidence demonstrating their ability to repay.
The increase suggests some borrowers are securing loans through exceptions to standard policies – although lenders still need to be satisfied they can afford the repayments.
Not meeting a lender's standard criteria doesn't necessarily mean you're out of options. Reach out and we can discuss whether another lender or a suitable exception pathway might be available.
I am a Mortgage Broker with over 30 years experience, I can help first home buyers buy their 1st home, home buyers buy their second, third or fourth home, investment property investors and people who want to build a home.
Based in Victoria Point, I have helped clients all over Australia purchase a home including Gold Coast, Brisbane, Cleveland, Redland Bay, Thornlands, Thorneside, Ormiston, Alexandra Hills, Sheldon, Mt Cotton, Victoria Point, Wellington Point, Birkdale, Shailer Park, Wynnum, Manly, Tingalpa and the greater Logan area.
Monthly Finance tips - September 26
- Details
 With another RBA decision just around the corner, borrowers have plenty to watch – from the risk of higher rates to falling property prices and a changing market for buyers. Here’s what to watch:
- Higher rental yields change the equation for investors
- How to prepare for a potential rate rise
- Buyers have more bargaining power – but there are limits
- What’s behind the record rise in broker market share?
Keep reading for all the news.
Call me now on: 0402 408944
Monthly Finance tips - July 26
- Details
 Higher interest rates, refinancing options and new government initiatives are reshaping the housing market. Here are four developments that could influence your next property decision:
- Help to Buy opens the door for more buyers
- What the new SMSF rules mean for investors
- Could you save thousands of dollars by refinancing?
- Don't let higher rates catch you out
Call me now on: 0402 408944
Monthly Finance tips - August 26
- Details
 Higher rates are squeezing household budgets, property prices are sliding and offset accounts are under scrutiny. Here are four stories worth knowing about right now:
- The hidden offset problem costing borrowers millions
- Cheaper homes are bucking the property downturn
- Housing rules blamed for holding back new supply
- Five ways to pay off your mortgage sooner
Keep reading for all the news.
Call me now on: 0402408944
Monthly Finance Tips - June 26
- Details
 The recent Reserve Bank decision isn’t the only big news. Here are four other stories that could influence your plans:
- The government scheme reshaping buyer behaviour
- What to know before building a home
- Electrified vehicles reach a new milestone
- Listings surge as buyers become cautious
Call me now on: 0402 408944
Koolee Industries Pty Ltd., ACN. 007 748 405, Credit Representative Number 398993
National Mortgage Brokers Pty Ltd., ABN 88 093 874 376, Australian Credit License 391209
Shane Khoo has access to a panel of lenders through National Mortgage Brokers Pty Ltd (ACN 093 874 376 / Australian Credit Licence 391209), which is a fully-owned subsidiary of Liberty Financial Pty Ltd (ACN 077 248 983 / Australian Credit Licence 286596). Shane Khoo has access to products including those from Liberty Financial.